For drivers on Long Island, understanding the difference between bodily injury and personal injury protection, also known as “PIP,” is important because both are required by law. The basic difference between the two is that bodily injury coverage pays for other people’s injuries when you cause an accident, while Personal Injury Protection (PIP) covers your own injuries regardless of who was at fault. Our experienced Long Island car accident attorneys break down the differences.
- Bodily Injury Insurance vs. Personal Injury Protection
- Bodily Injury Liability Coverage
- PIP Coverage
- How to Seek Additional Compensation for a Serious Physical Injury
Bodily Injury Insurance vs. Personal Injury Protection
In New York, bodily injury coverage is a type of liability insurance you are required to carry in your car insurance to compensate a third party for damages if you are responsible for an accident. PIP insurance, also known as no-fault insurance, is a different type of insurance you are required to carry that covers you if you are injured in an accident, regardless of who was at fault.
New York State law requires drivers to carry a minimum of $25,000 in bodily injury coverage and $50,000 in PIP coverage in their auto insurance policies.
Bodily Injury Liability Coverage
Bodily injury liability covers you and anyone who has permission to drive your car if an accident claim is made against you by a third party. This type of insurance policy coverage will make payments on your behalf to a third party if your car is involved in an accident that results in serious injury, death, or damage to someone else’s property. It is also the coverage you pursue against another party who caused your injuries in an accident.
Legal Defense
A bodily injury liability insurance policy will also ensure that your insurance company will provide you with a legal defense against a bodily injury claim alleging that you were negligent or at fault for an accident.
Bodily Injury Liability Coverage Minimums in New York
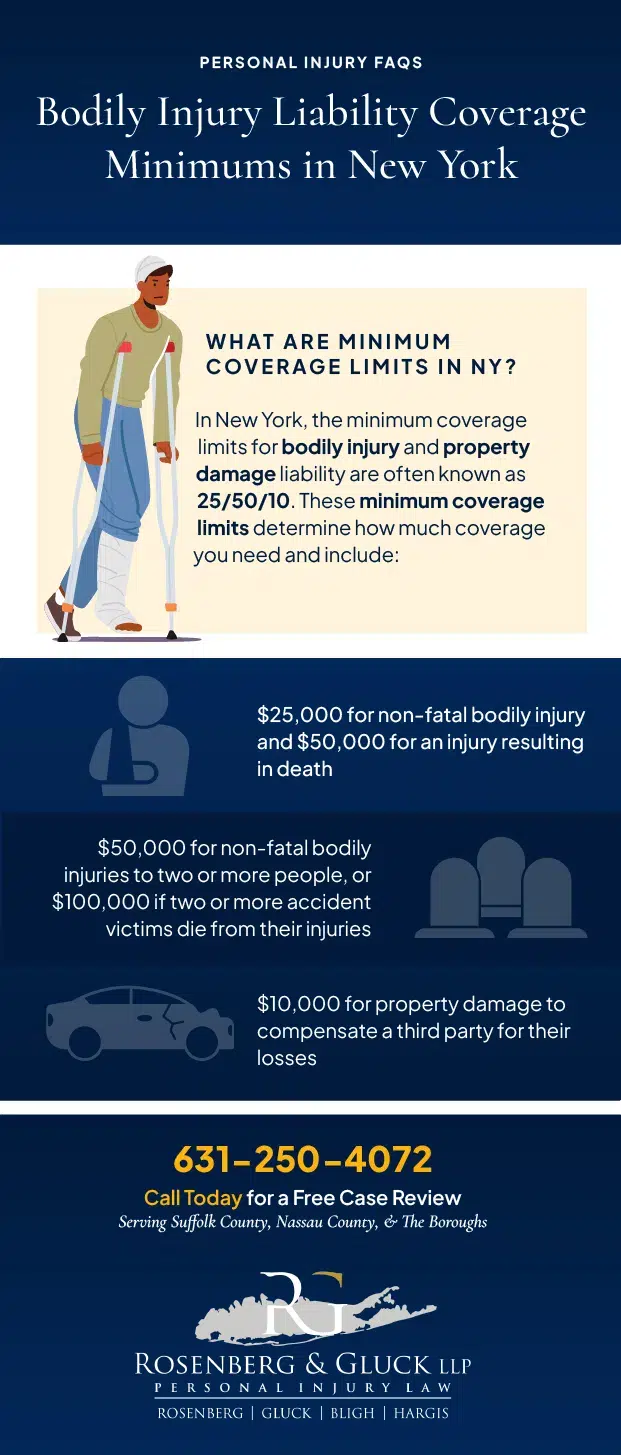
In New York, the minimum coverage limits for bodily injury liability coverage and property damage liability coverage are often referred to as 25/50/10. These minimum coverage limits determine how much coverage you need and include:
- $25,000 for bodily injuries that do not result in death or $50,000 for an injury that results in the death of a person injured in an accident
- $50,000 for physical injuries that do not result in death sustained by two or more people involved in an accident or $100,000 for an injury that results in the death of two or more accident victims
- $10,000 for property damage liability protection to compensate a third party for damage to their property
PIP Coverage
PIP or no-fault coverage in New York is designed to pay for your basic economic losses from a car accident, regardless of who is at fault and whether or not there was any negligence. Basic coverage will pay up to $50,000 per person to the driver and any passengers who were injured, as well as to injured pedestrians or cyclists struck by the vehicle.
Types of Economic Damages Covered by PIP in Personal Injury Cases
This type of policy will cover economic losses, including medical bills, healthcare and medical expenses, and lost wages. It will also cover other reasonable and necessary expenses related to the injuries sustained in the accident by the driver, passenger, pedestrians, or cyclists.
What Basic No-Fault Auto Insurance Covers
After a motor vehicle accident, basic no-fault insurance will cover you for:
- Your own medical expenses that are reasonable and necessary for the injuries you suffered in your accident; no-fault is your primary health insurance and will pay your medical bills first
- 80% of your lost income with a maximum of $2,000 per month for up to three years from your car accident
- A reimbursement up to $25 per day up to a year after the accident for other reasonable and necessary expenses, which could include things like housekeeping help and transportation expenses
- A $2,000 death benefit paid to the estate of the person killed in an accident, which is in addition to the $50,000 no-fault, per-person limit
What PIP Doesn’t Cover
Economic losses due to a serious injury that exceeds the no-fault benefits limit of $50,000 will not be covered by PIP insurance. These damages may be recovered in a personal injury lawsuit along with other non-economic damages like pain and suffering, loss of enjoyment of life, scarring and disfigurement, and more.
No-fault also does not pay for property damage like auto body repair work on your damaged car or compensation for the other driver’s wrecked car. It also does not cover motorcyclists.
Ineligibility for No-Fault Benefits
Under most insurance policies, a person could be ineligible for no-fault benefits if they were:
- Drunk driving or driving under the influence of drugs
- Committing a felony or fleeing from the police
- In a stolen vehicle or one that is not insured adequately
- Intentionally causing the injuries
- Riding a motorcycle or ATV as the driver or a passenger
How to Seek Additional Compensation for a Serious Physical Injury
If your damages are greater than your PIP coverage limits, you may be able to file a personal injury lawsuit to seek additional compensation. A personal injury lawyer can help you understand your rights and options under New York State law.
Call Our Personal Injury Law Firm Today
Call today for a free legal consultation to discuss your personal injury case. We work on a contingency fee basis. You pay no legal fees unless we win.
For A Free Legal Consultation, Call